Would Tarnița-Lăpuștești make money on Romania's power market?
If the 1,000 MW pumped hydro plant had already existed in the Someșul Cald mountains, what would it have earned day by day? We ran the plant, interval by interval, across actual DAM clearing prices from 2019 to 2026.
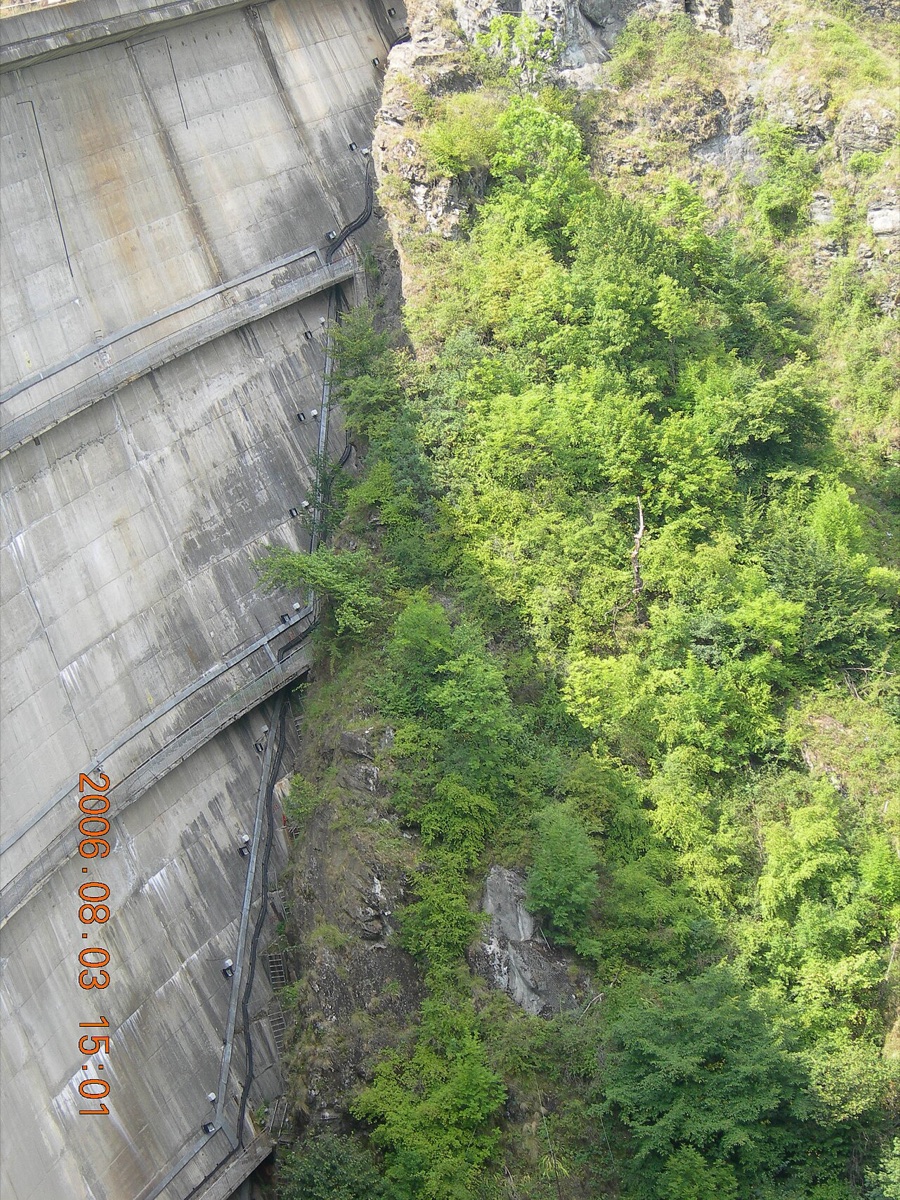
Below, “Tarnița” is shorthand for the full Tarnița-Lăpuștești project. Tarnița dam and lake exist and would form the lower reservoir; the upper Lăpuștești reservoir and pumped-storage plant are designed but unbuilt. Older engineering parameters are labelled “historical design basis” — they are not necessarily the final EDF/Hidroelectrica design.
2026 is a partial year and never enters averages.
What this model actually tests
- historical DAM energy arbitrage
- storage losses (RTE)
- power and storage constraints
- the perfect-foresight upper bound
- transparent capture and spread sensitivities
- simplified capital-recovery economics
- full intraday optimisation
- balancing and reserve revenue
- ancillary-service revenue
- endogenous Romanian market re-clearing
- network congestion and financing structure
- hydraulic curves, geotechnical risk, project EIA
A transparent historical-counterfactual and project-economics model, not a feasibility study or an investment-grade bankability model.
Hydraulic cross-section of Tarnița-Lăpuștești
Mountain profile: over 500 metres of gross vertical head between the Lăpuștești plateau and Lake Tarnița. Figures are the historical design basis.
How much energy can Tarnița actually store?
In public discussion Tarnița is often reduced to a single number: a “5 GWh battery”. The design documentation does not say that. It speaks of four different things, and blurring them distorts the economics.
| Concept | Value | What it means |
|---|---|---|
| 1. Installed power | 1,000 MW | Four 250 MW reversible units (historical design basis). |
| 2. Useful upper volume | 10m m³ | Useful volume of the upper Lăpuștești reservoir in the historical design; minimum operating level is about 0.35m m³. |
| 3. EPDC five-hour criterion | 1,000 MW × 5 h | Documented continuous-operating capability. Not evidence that only five hours of useful volume exist. |
| 4. Legacy weekly cycle | weekly fill/empty | The designed operating regime fills and empties the lake over a weekly pattern — not a simple daily battery. |
At maximum turbine flow (4 × 53 m³/s), the useful volume would last about 13 hours. This is useful physical intuition, not a certified electrical rating: actual electrical energy depends on head, efficiency, operating levels and final equipment characteristics.
For the market model we use a transparently derived storage ceiling from these values — 13,100 MWh of output-equivalent energy — explicitly marked as a simplified model parameter, not an official nameplate. The “5 hours” figure is EPDC's continuous-operating criterion; it should not be read as evidence that only five hours' worth of useful volume exists.
The round-trip toll: what pumped water costs
Pumped hydro produces no net energy; it moves energy through time at a loss. Water friction in the galleries, transformer losses and reversible-unit efficiency impose a physical cost: round-trip efficiency (RTE).
At the central RTE of 78.4%, delivering 1 MWh at peak requires pumping 1.28 MWh in cheap hours. If Tarnița buys at €30/MWh, discharged energy already costs €38.3/MWh — before any capital cost.
The model does not use one “true” efficiency but three transparent cases — and every result on the page recomputes when you switch case:
Play one day on the Romanian grid
Take the controls of Tarnița-Lăpuștești for 24 hours. Every scenario is an actual delivery day with the DAM prices observed then — not a generated curve. Older days are hourly, newer ones quarter-hourly, exactly as the market ran.
The game uses the same model as the historical backtest: the same storage accounting, the same selected RTE case, the same 13,100 MWh ceiling.
…
……
…
Energy prices and operating schedule across the selected day
Water left in store at midnight earns no value credit: the day starts empty and ends with at most 75 MWh left (neutral boundary condition).
Running Tarnița on the real market (2019–2026)
We simulated every market interval chronologically — 92,852 observations — carrying storage from one day to the next. The headline result is the perfect-foresight upper bound: how much DAM arbitrage was available with perfect hindsight, under the stated constraints. 2026 is partial (1 January – 16 September) and never enters averages.
Not a forecast-accuracy estimate. Asks what remains if the operator captures only X% of the ex-post optimal value.
A scenario sensitivity (margin × (1 − compression)), not an estimate of Tarnița's equilibrium price impact.
| Year | Avg DAM (€) | Avg spread (€) | Scenario margin (€) | Discharged (TWh) | EFC | Negative hours | Top 10% of revenue |
|---|
Table margins apply the selected scenario (capture × compression) on top of the ex-post optimum. Official OPCOM annual averages are reproduced by the dataset within rounding tolerance (see Methodology).
How much revenue does the modelled market leave uncovered?
On 27 January 2026, Hidroelectrica shareholders approved a 50/50 association with EDF Power Solutions International to develop the Tarnița project. That is project-development status — not a Final Investment Decision, not a construction commitment, not an approved final technical design: pre-feasibility (~€400,000) and the studies to FID (~€30m) still lie ahead.
The correct economic question has three layers: (A) the commercial revenues modelled here — DAM arbitrage; (B) potential unmodelled revenues — intraday, balancing, reserves, system services, availability contracts; (C) the simplified annual capital + OPEX requirement. The gap between (C) and (A) is the residual annual revenue requirement in this model — not automatically a subsidy, not automatically a failure.
Simple annual capital-recovery test
How much annual revenue from outside DAM arbitrage (balancing, reserves, system services, contracts) would close the requirement? Drag to see the bridge.
The test annuitises CAPEX, adds OPEX and subtracts the selected-scenario DAM margin. Excluded: drawdown schedule, interest during construction, debt/equity structure, taxes, fiscal depreciation, refinancing, reserve accounts, cost overruns, commissioning ramp, revenue contracts and the full revenue stack. It is not a lender-grade bankability model.
How infrastructure revenues could, in principle, be stabilised
Educational section: the concepts below explain the forms through which energy infrastructure stabilises revenues in general. This page designs no contractual schemes and computes no sign-ready strike prices or guaranteed payments.
Availability / capacity payment. A payment for firm available MW regardless of energy traded — it remunerates the capacity's existence, not its output.
Contract for difference (CfD). A reference price against which differences settle periodically; the real design (settlement basis, eligible volumes, risk allocation) is an entire legal construction, not one LCOS number.
Regulated asset base (RAB). Recognised assets earn a regulated return; volume and spread risk move, by design, onto consumers.
System services: what we know, what we suspect, what we quantify
| Service / capability | Documented status | Quantified in this model? |
|---|---|---|
| DAM arbitrage (energy shifting) | Documented pumped-storage mechanism | YES — the only modelled revenue |
| Secondary / tertiary reserve | Assessed in the historical design studies | NO — no revenue quantified here |
| Reactive power / voltage support | Technical capability in the historical documentation | NO |
| Rotating inertia | Potential, depending on final machine topology and inertia constant H | NO — no inertia figure computed |
| Black start | Relevant function in the historical documentation; a potential capability if specified and equipped in the final design | NO |
| Renewable curtailment reduction | Plausible system effect under some conditions | NOT QUANTIFIED — needs system modelling |
| Wholesale price effect | Possible endogenous effect | NOT MODELLED — compression sensitivity only |
What would change the conclusion?
Four thresholds computed from the model's own maths, for the currently selected scenario. Each answers: how far must one variable move for the simplified test to clear exactly?
The storage race: Tarnița vs. battery parks
While Tarnița stayed on the drawing board, Romania's grid saw an unprecedented electrochemical battery (BESS) build-out. As of 1 September 2026, Transelectrica figures show 1,094 MW of power and 2,310 MWh of energy (connected and commissioning capacity).
MW measures instantaneous power, while MWh measures energy delivered over time. Romania's batteries average about 2.1 hours of duration; Tarnița's market model uses a derived 13,100 MWh ceiling (≈13.1 hours at 1,000 MW), and the EPDC criterion calls for 5 continuous operating hours.
Levelised-cost (LCOS) frontier
Which technology has the lower modelled LCOS, by discharge duration and annual cycling. Both sides use the same discount rate, the same charging-energy price and the same currency (EUR).
…
Assumptions: the battery has 85% AC–AC round-trip efficiency, at most 15 years of life and about 4,000 full cycles; fixed O&M is 2.5% of CAPEX (including augmentation, NREL ATB 2024 framework). Pumped hydro uses the selected RTE case, a 60-year financial life and the same OPEX as the capital test. Battery costs follow an illustrative decline path (see the assumption inspector). LCOS is computed inside this model — it is not an NREL or BNEF figure. LCOS does not value every system service and should not be read as a complete technology ranking.
The uncertainty laboratory: 1,000 scenarios of your choosing
Underground megaprojects systematically overrun budgets and schedules. The deterministic thresholds above show where break-even sits; the laboratory below shows how often it would be reached under distributions you choose. The result is conditional on the ranges you set — it is not an estimated real-world probability.
Net present value (NPV) distribution under your scenarios
Each variable is drawn uniformly from the range you set. Construction is spread over the build duration, and 40 operating years start after commissioning. Deterministic seed … — the initial result is reproducible; “Resample” draws another 1,000 scenarios.
What is actually built on the Someșul Cald?
Tarnița's engineering scale is often overshadowed by financial debate. The historical project involves major civil intervention in the Gilău Mountains: shafts, galleries and an underground machine hall, with large volumes of excavated rock.
The Strategic Environmental Assessment (SEA, 2019) prepared for Romania's energy strategies mapped a possible intersection of the project's historical footprint with two Natura 2000 network sites:
- ROSCI0263 Valea Ierii and ROSCI0427 Pajiștile de la Liteni–Săvădisla — a finding of a 2019 strategic exercise over a historical footprint, not a conclusion about the final design nor a substitute for project-level impact assessment (EIA) and appropriate assessment, which would follow.
Water, levels, shorelines: what is documented and what needs assessment
DOCUMENTED CONDITION Tarnița sits inside the Someșul Cald cascade that supports downstream water supply. Historical project documentation notes downstream potable and industrial water requirements and identifies the Gilău reservoir as supplying the Cluj-Napoca water-treatment plant.
TO ASSESS Large transfers between the two reservoirs could affect operating levels and, through them, turbidity, shoreline stability and recreation — matters for coordinated hydrological and environmental assessment, not figures established here.
NOT QUANTIFIED HERE No environmental impact is quantified in this economic model.
The grid it was designed for vs. the grid it would enter
The geography is unchanged after fifty years. But the economic problem Tarnița was conceived to solve in the 1970s looks nothing like the reality of today's power market.
Solar duck curve and 15-minute market settlement
Today, nighttime is no longer the sole low-price period. Surging solar and prosumer output depress noon prices (frequently into negative territory), followed by steep evening ramps at sunset. Competition comes not from coal plants, but from modular battery arrays deployed directly at grid nodes.
Data and assumptions catalog
Every important number on the page belongs to one of the categories below. Click any row (or the ⓘ in the text) for source, model role and sensitivity.
| Parameter | Value | Status | Source / basis |
|---|
The full interval series (92,852 observations) is not redistributed under the data mirror's licence; the manifest shows how to reproduce and validate it. Representative days and annual outputs are published derivatives with provenance.